which sydney suburbs are affordable for first home buyers right now?
here's the honest version. in sydney, "affordable" almost never means a freestanding house close to the cbd. it means an apartment or a townhouse, and it means looking along the outer corridors where prices have always sat lower than the inner ring. that's not a downgrade, it's just how the biggest, most expensive city in the country works.
the corridors first home buyers keep landing in tend to be the outer west and south-west (think the broad penrith, mount druitt, liverpool and campbelltown directions), pockets of the far north-west near the growth centres, and the central coast end of the commute where gosford and the surrounding suburbs pull the entry price down again. units in parts of parramatta, blacktown and the wider western sydney middle ring also come up at entry-level numbers more often than houses do.
i'm deliberately not quoting suburb prices as fact, because in sydney they move fast and a number i write today can be wrong by the time you read it. what i'd do instead is treat the suburb names above as a starting map, then open current listings, filter to your real budget, and watch what actually transacts. the suburbs that fit your number will reveal themselves quickly, and they may not be the famous ones.
the honest part
in sydney, affordable almost never means a freestanding house close to the cbd. it means an apartment or townhouse along the outer corridors, and that is a real foothold, not a downgrade.what counts as affordable in sydney in 2026?
affordable is relative to the city, and sydney is the most expensive city in australia, so the bar sits higher here than anywhere else. for a first home buyer, i'd define affordable as a property you can actually service, with a deposit you can realistically save, where the repayments don't swallow your whole life.
in practice that usually points you at apartments and townhouses rather than houses, and at the outer corridors rather than the inner suburbs. an "affordable" sydney first home is often a one or two bedroom unit, or a smaller townhouse, in a growth area with a longer commute. that's not failure, that's a foothold, and a foothold in sydney is genuinely hard-won.
the other half of affordable is what the bank will lend you and what the government schemes will let you buy. a price can look affordable on paper and still be out of reach because your borrowing capacity caps out lower, or because the property sits above a scheme price cap. so when you ask "is this affordable", i'd answer it in three parts: can i save the deposit, can i service the loan, and does it fit the caps. all three have to line up.
worth knowing
ask is this affordable in three parts: can i save the deposit, can i service the loan, and does it fit the scheme caps. all three have to line up before a price is really within reach.affordable suburbs in sydney under $800k (by region)
under $800k in sydney is real, but it lives in specific directions, and mostly in units and townhouses rather than houses. here's how i'd think about it by region, as a map to go and verify against current listings rather than a price list.
west and south-west: this is the deepest pool of entry-level stock. the broad penrith, st marys, mount druitt, blacktown, liverpool and campbelltown corridors are where a lot of first home buyers find units and the occasional townhouse inside budget. parramatta units come up too, though houses there will sit well above the line.
north-west and growth centres: the newer release and growth areas out past the established north-west can offer townhouses and units at entry level, often brand-new, which can also matter for stamp duty concessions on new builds. check the current rules, because what you pay can differ for new versus established.
central coast fringe: if a longer commute is acceptable, the gosford end of the central coast stretches a sydney-region budget further, and you'll see houses, not just units, come into range more often there.
wherever you look, i'd repeat the same discipline. don't trust a remembered price, open current listings, filter to your number, and watch what's actually selling. the regions above tell you where to point the search.
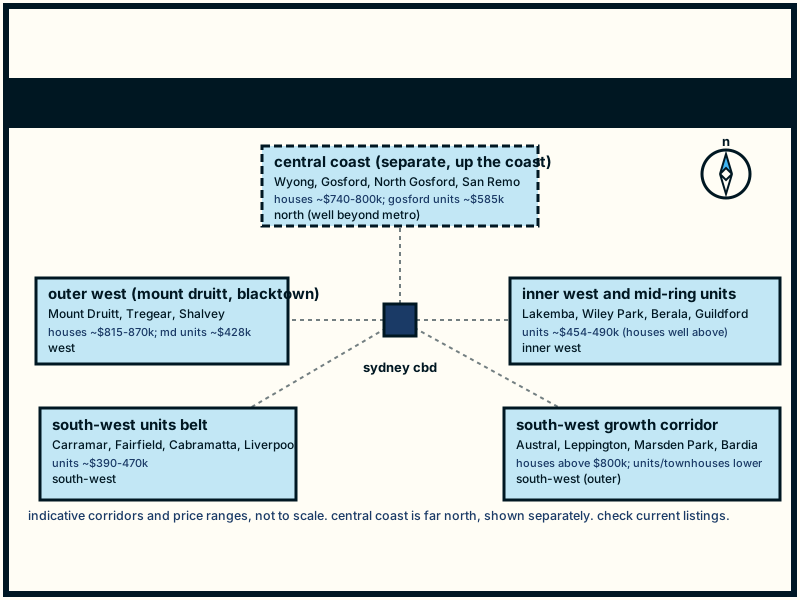
| corridor | example suburbs | indicative range |
|---|---|---|
| the south-west units belt | Carramar, Canley Vale, Fairfield, Cabramatta | units roughly $390k to $470k |
| the outer west (mount druitt and blacktown fringe) | Mount Druitt, Tregear, Lethbridge Park, Willmot | houses roughly $815k to $870k and Mount Druitt units around $428k |
| the inner west and mid-ring units | Lakemba, Wiley Park, Berala, Guildford | units roughly $454k to $490k |
| the south-west growth corridor | Austral, Leppington, Marsden Park, Bardia | new freestanding house-and-land mostly above $800k, with smaller lots, townhouses and units the under-$800k play (for example Bardia units around the high $700k mark, indicative, check current listings) |
| the central coast | Wyong, San Remo, North Gosford, Gosford | Wyong houses around or just under $800k and edging up, San Remo houses around $740k to $792k, North Gosford houses around $743k, Gosford units around $585k |
| region | rough direction | what tends to fit the budget |
|---|---|---|
| west and south-west | penrith, st marys, mount druitt, blacktown, liverpool, campbelltown | deepest pool of entry-level units, the occasional townhouse |
| north-west and growth centres | newer release areas past the established north-west | townhouses and units, often brand-new, which can matter for stamp duty on new builds |
| central coast fringe | the gosford end of the central coast | houses come into range more often, in exchange for a longer commute |
first home buyer schemes that apply in sydney and nsw
buying in sydney means you're buying in new south wales, so you've got two layers of help to check. the state layer is run by nsw (a first home buyer grant and stamp duty concessions, both covered in the scheme summaries on this page), and the federal layer (the home guarantee schemes, including the first home guarantee with its own sydney price cap) runs nationally but applies here too.
the key thing i want you to take away is that these schemes stack and they each have their own rules, eligibility and price caps. a property might qualify for a stamp duty concession but sit above the first home guarantee cap, or the other way around. you don't get to assume, you have to check each one against the actual property.
the deep detail on the federal guarantee schemes lives on the dedicated pillar pages, and the relevant podcast episodes walk through how real buyers used them. on this page, start with the dated nsw scheme summaries below, then click through to the pillars to go deeper. and because the numbers and caps change, always confirm the current figures on the government source before you budget around them. this is general information, not advice for your situation.
| layer | who runs it | what it covers |
|---|---|---|
| state (nsw) | revenue nsw | first home buyer grant on new homes, plus stamp duty (transfer duty) concessions |
| federal | national, applies in nsw too | home guarantee schemes, including the first home guarantee with its own sydney price cap |
one to watch
these schemes stack but each has its own rules and caps. a property might qualify for a stamp duty concession yet sit above the first home guarantee cap, or the other way around, so check each one against the actual property.nsw stamp duty for first home buyers, what you do and do not pay
stamp duty (in nsw it's transfer duty) is one of the biggest upfront costs of buying, and it's exactly where nsw gives first home buyers a break. the state runs first home buyer stamp duty concessions, which can mean you pay no transfer duty up to one price threshold, and a reduced amount in a band above that, before full duty kicks in at the top. it can differ for new homes, established homes and vacant land.
what i won't do is quote you the thresholds as fact, because nsw adjusts them and i don't want you budgeting off a stale number. the principle is what matters: below a certain price you may pay nothing, in a middle band you may pay a reduced amount, and above the cap you pay the standard duty like any buyer. so the price you choose directly changes your stamp duty bill, and a few thousand dollars over a threshold can cost you a lot in duty.
what i'd do is check the current nsw transfer duty thresholds on revenue nsw before you set your budget, and factor the duty (or the saving) into your real cost. it's also worth knowing the concession has eligibility conditions, like living in the home for a set period, so read those too. the dated nsw stamp duty summary below gives you the framing and the government source. this is general information only, check the current rules for your purchase.
rough framing only. nsw adjusts the thresholds and they can differ for new homes, established homes and vacant land, so check the current figures on revenue nsw before you budget.
the bit i'd flag
a few thousand dollars over a threshold can cost you a lot in duty, so the price you choose directly changes your stamp duty bill.how much deposit do you need to buy in sydney?
the textbook answer is twenty percent of the purchase price plus your costs, and at sydney prices that's a very big number, which is exactly why most first home buyers here don't do it that way. the more useful answer is that your minimum deposit depends on which path you take.
with a standard loan, lenders generally want twenty percent to avoid lenders mortgage insurance (lmi), but you can usually buy with less and pay lmi, which adds to your cost but gets you in sooner. with the federal first home guarantee, eligible buyers can purchase with a much smaller deposit and the government guarantees the gap so you avoid lmi, and that's often the difference between buying now and saving for years more. the guarantee has its own sydney price cap, covered below and on the pillar.
so "how much deposit" really becomes "which path, and what does that path require". on top of the deposit itself, budget for stamp duty (or your concession), conveyancing, building and pest inspections and the small ongoing costs. i'd work out your deposit target backwards: pick the path, apply its rules to the price range you're looking at, and that gives you the real number to save toward. the deep deposit guidance lives on the deposit pillar page.
general framing only. the right path depends on your borrowing capacity and the current scheme rules, and you still budget for stamp duty, conveyancing and inspections on top.
grab my deposit roadmap
the same backwards method i use to set a real deposit target once you have picked your path and your price range.
what the first home guarantee price cap means in sydney
the first home guarantee is the federal scheme that lets eligible first home buyers purchase with a smaller deposit and skip lenders mortgage insurance, with the government guaranteeing the shortfall. the catch that matters most in sydney is the price cap. the scheme sets a maximum property price by location, and sydney has its own (higher) cap because it's the most expensive market in the country.
in plain terms, the cap is a ceiling. if the property you want sits at or under the sydney cap and you meet the other eligibility rules, the guarantee can be in play. if it sits above the cap, this particular scheme can't help with that purchase, even if everything else fits. so in sydney the cap quietly shapes which suburbs and which property types are realistically on your list, which is another reason the affordable corridors above matter.
i'm not going to print the cap figure here, because it's reviewed and changed periodically and i'd rather you confirm the live number than trust a stale one. what i'd do is check the current sydney price cap on the official government source, then use it as a hard line when you filter listings. the full how-it-works, including eligibility and how it stacks with the nsw concessions, is on the first home guarantee pillar. this is general information only, check the current rules.
the cap is a hard line
if the property sits at or under the sydney cap and you meet the other rules, the guarantee can be in play. above the cap, this scheme cannot help, even if everything else fits, so it quietly shapes which suburbs and property types are on your list.
watch: john and nicola walk through how the guarantee actually works and how the cap plays out.
how to shortlist a sydney suburb on a first home budget
once you've got your real budget and you know your scheme caps, shortlisting gets practical. here's roughly what i'd do, in order.
start with the number, not the suburb. set your actual borrowing capacity plus deposit, subtract stamp duty (or your concession) and buying costs, and that's the price you can shop to. then apply the relevant scheme cap as a ceiling, because there's no point shortlisting above it.
then point the search at the corridors, not the whole city. use the regions above (west, south-west, north-west growth areas, central coast fringe) and the property types that actually fit the budget, which in sydney usually means units and townhouses. open current listings and watch what genuinely transacts in your range, not what's optimistically listed.
finally, pressure-test the lifestyle, not just the price. check the real commute at peak times, the transport links, what's being built nearby, and whether the place suits how you actually live. an affordable suburb you can't stand commuting from isn't a win. when you've got two or three areas that fit the number and the life, that's your shortlist. if you want a second set of eyes on the numbers and the scheme stacking, you can book a chat with the team at finance lab, they do this every day.
nsw first home buyer grant (first home owner grant, new homes)
new south wales runs a first home owner grant for eligible first home buyers purchasing or building a new home (not established homes), administered by revenue nsw. it's a one-off payment with a property value cap and eligibility conditions, including a requirement to live in the home for a set period. amounts, value caps and eligibility are set by the nsw government and can change, so i'm not quoting a figure here. check the current grant amount, the property value cap and the eligibility rules on the official source before you rely on it. government source: revenue nsw, first home owner grant (new homes), revenue.nsw.gov.au. general information only, current as at june 2026, confirm the live rules for your purchase.
last reviewed june 2026
nsw stamp duty (transfer duty) concession for first home buyers
nsw offers first home buyer transfer duty (stamp duty) concessions through the first home buyers assistance scheme, administered by revenue nsw. eligible buyers may pay no transfer duty up to one price threshold and a reduced amount in a band above it, with full duty applying above the cap, and the thresholds can differ for new homes, established homes and vacant land. there are eligibility conditions, including living in the property for a set period. the thresholds and rules are set by the nsw government and are adjusted over time, so i'm not printing numbers here. check the current transfer duty thresholds and eligibility on the official source before budgeting. government source: revenue nsw, first home buyers assistance scheme, revenue.nsw.gov.au. general information only, current as at june 2026, confirm the live rules for your purchase.
last reviewed june 2026
 hear it on the showbreaking down the first home guarantee scheme
 hear it on the showhow to find properties below $500k
 hear it on the showwhat you need to know about cooling off periods when buying property
also by location: what it costs to buy a first home first home buyer New South Wales
frequently asked questions
what are the cheapest suburbs in sydney to buy a first home?
the lowest entry prices in sydney sit in the outer corridors, mostly the west and south-west (around penrith, mount druitt, liverpool and campbelltown), parts of the north-west growth areas, and the central coast fringe near gosford, and they're usually units and townhouses rather than houses. i won't name set prices because sydney moves fast, so treat those as a map and check current listings filtered to your budget. this is general information only, confirm the latest with a quick search before you commit.
do first home buyers pay stamp duty in nsw?
often less, sometimes nothing, but it depends on the price. nsw gives first home buyers transfer duty concessions through the first home buyers assistance scheme, so you may pay no duty up to one threshold, a reduced amount in a band above it, and full duty above the cap, with conditions like living in the home for a set period. the thresholds change, so check the current figures on revenue nsw before you budget. general information only, not advice for your situation.
what is the first home guarantee price cap in sydney?
sydney has its own (higher) price cap under the federal first home guarantee, because it's the most expensive market in the country, and the cap is the maximum property price the scheme will cover. i'm not quoting the figure because it's reviewed and changed periodically, so check the live sydney cap on the official government source and use it as a hard ceiling when you filter listings. this is general information only, confirm the current cap and your eligibility before relying on it.
how much deposit do i need to buy a first home in sydney?
it depends on your path. a standard loan generally wants twenty percent to avoid lenders mortgage insurance, but you can usually buy with less and pay lmi, and eligible buyers using the federal first home guarantee can purchase with a much smaller deposit and skip lmi (subject to the sydney price cap). budget for stamp duty or your concession and buying costs on top. work the number backwards from your path, and check the current scheme rules, this is general information only.
can you buy a first home in sydney under $800k?
yes, it's real, but mostly in units and townhouses in the outer corridors, the west and south-west, the north-west growth areas and the central coast fringe, rather than freestanding houses near the cbd. i'd point your search at those regions, filter current listings to your number, and watch what actually transacts. prices move, so this is general information only, verify the live market before you set your heart on a figure.
what is a realistic first home budget in sydney in 2026?
a realistic budget is whichever number lines up across three things at once: the deposit you can actually save, the loan you can comfortably service, and the relevant scheme price caps. sydney is the most expensive city in australia, so for many first home buyers that lands on a unit or townhouse in an outer corridor rather than a house close in. i won't put a single dollar figure on it because your borrowing capacity and the caps drive it, this is general information only, run your real numbers (a chat with finance lab can help).
general information only, not personal financial advice. Finance Lab, Credit Representative Number 425945, authorised under Australian Credit Licence Number 389328. scheme, grant and cost figures are explanatory only, change regularly, and were last reviewed june 2026. always confirm current rules with the relevant government source.