which brisbane suburbs are affordable for first home buyers right now?
let me start with the honest version, because the brisbane you see on a property show is not the brisbane most first home buyers actually buy in. the inner ring, your new farms and paddingtons and west ends, is not where an entry budget goes. affordable, for a first home buyer, almost always means one of two things: you go further out along the rail and motorway corridors, or you look at unit and townhouse stock closer in rather than a freestanding house.
the pattern that holds in brisbane is corridors, not single suburbs. heading south and south-east you've got the logan corridor and the areas running down toward the gold coast hinterland. heading west and north-west there's the ipswich corridor and the springfield growth area. heading north you've got the suburbs running up toward moreton bay and caboolture. these are the places where an entry house budget still buys you a house, and where the under-$600k brackets genuinely exist rather than being a rounding error.
closer in, the trade is house for unit. a two-bedroom unit or townhouse in a middle-ring suburb can land in a similar price band to a house an hour out, and for a lot of first home buyers that's the better life: shorter commute, less to maintain, closer to where they already work. neither path is the "right" one. it depends on whether your priority is land and space or location and convenience.
i'm not going to name a suburb and a price as fact, because brisbane prices move fast and a number i write today can be wrong in a few months. what i'd do is treat the corridors above as your search zones, then check current listings yourself in those areas to see what your budget actually opens the door to this month.
watch: where an entry budget actually buys in brisbane, and the deposit it takes to get in
the honest part
the brisbane you see on a property show is not the brisbane most first home buyers buy in. affordable usually means going further out along the rail and motorway corridors, or trading a house closer in for a unit or townhouse.what counts as affordable in brisbane in 2026?
"affordable" only means something against your own numbers, so here's how i'd think about it rather than a single headline figure. affordable is the price where the repayments still fit your life after you've factored in rates, insurance, body corporate if it's a unit, and the boring running costs nobody mentions at the open home. a place you can technically get a loan for is not the same as a place you can comfortably live in.
in brisbane, the entry brackets people actually shop in cluster well under the citywide median. that's why this page is built around the under-$600k question: it's the band where the outer corridors and the unit market overlap with what first home buyer borrowing power and a deposit can realistically reach. it's not the only band, but it's the one where the most genuine first home options sit.
the other half of affordable is the schemes. a queensland first home buyer who qualifies for a transfer duty concession and a deposit scheme that may waive LMI is effectively shopping with a different budget than someone paying full duty and full lenders mortgage insurance. so "what's affordable" isn't just the sticker price, it's the sticker price minus the help you may be entitled to. work out the help first, then the price band, then the suburb. doing it in that order is how you avoid falling for a place you can't actually swing.
affordable suburbs in brisbane under $600k (by region)
rather than a list of postcodes that'll date the second a market moves, here's the under-$600k map by direction, so you know where to point your search.
south and south-east, the logan corridor is the classic first home buyer zone: this is where an entry house budget still buys a freestanding house with a yard, and where the largest pool of sub-$600k houses tends to sit. it stretches a fair way, so the deal you can find improves the further out you're willing to go.
west, the ipswich corridor and the springfield growth area give you a mix of established houses and newer house-and-land stock. springfield in particular was master-planned, so you get newer homes, schools and rail, which suits buyers who want a turn-key place rather than a renovator.
north, the moreton bay region running up toward caboolture and the surrounding suburbs is the northern equivalent of logan: established houses in the entry brackets, with the bayside lifestyle as the draw.
closer in, across the middle ring in most directions, the under-$600k stock shifts from houses to two-bedroom units and townhouses. if location beats land for you, this is your region, and it cuts across the map rather than sitting in one corner.
i'd treat each of those as a search zone, not a recommendation, and i'd check current listings in two or three of them before deciding which direction your money goes furthest. the right region is the one where your budget, your commute and your life actually line up, and that's personal.
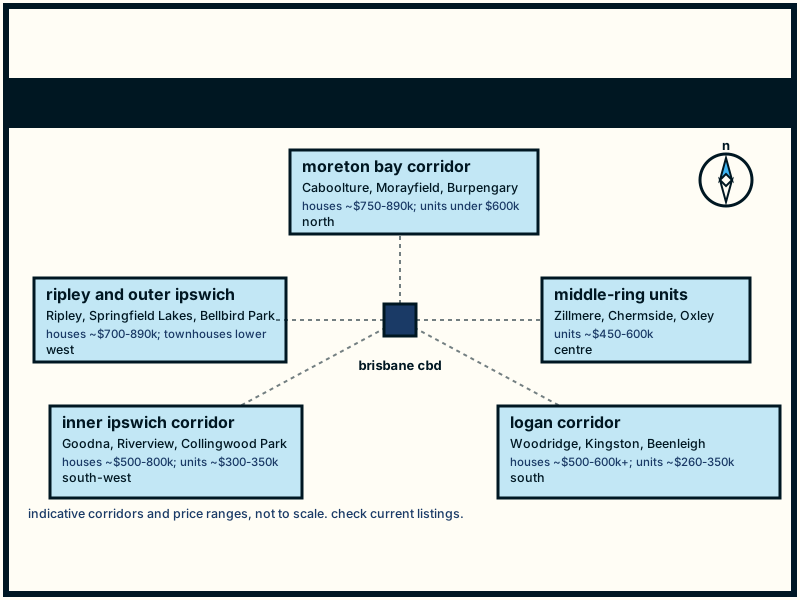
| corridor | example suburbs | indicative range |
|---|---|---|
| the logan corridor (south) | Woodridge, Logan Central, Kingston, Crestmead | Brisbane's lowest-priced house market overall; entry-level houses still found from around $500k to $600k in the cheaper pockets, though suburb medians now range from roughly the low $500k range up to around $750k to $850k depending on the suburb; units from around $260k to $350k |
| the inner ipswich corridor (south-west) | Goodna, Riverview, Dinmore, One Mile | among the lower house entry prices in greater Brisbane, with entry-level homes still found from around $500k to $600k in cheaper pockets; suburb medians now sit higher, roughly the high $500k range up to around $800k depending on the suburb and source; units around $300k to $350k |
| the ripley valley and outer ipswich (south-west growth corridor) | Springfield Lakes, Ripley, Redbank Plains, Bellbird Park | master-planned growth corridor where house medians have moved up sharply and now mostly sit above $600k; under $600k buying here is increasingly an older house, a townhouse, or a smaller block (indicative, check current listings) |
| the moreton bay corridor (north) | Morayfield, Caboolture, Burpengary, Deception Bay | houses now mostly above $600k, so under-$600k buying here is largely units and townhouses (indicative, check current listings) |
| middle-ring units (closer in) | Zillmere, Chermside, Nundah, Oxley | units indicatively around $450k to $600k at the lower end, though some (Nundah, Woolloongabba) now push above $600k; houses in these suburbs are generally well above an under-$600k budget |
| direction | the corridor | what you tend to get |
|---|---|---|
| south / south-east | logan corridor | largest pool of entry houses with a yard, better the further out you go |
| west | ipswich and springfield growth area | mix of established houses and newer house-and-land, schools and rail |
| north | moreton bay toward caboolture | established entry houses with a bayside lifestyle draw |
| closer in | middle ring, most directions | two-bedroom units and townhouses if location beats land for you |
first home buyer schemes that apply in brisbane and queensland
if you're buying your first home in brisbane, there are two layers of help to know about: federal schemes that apply anywhere in australia, and queensland-specific schemes that stack on top. you don't have to memorise them, you just have to know they exist so you don't leave money on the table.
the federal layer includes the australian government 5% deposit scheme (the scheme formerly called the first home guarantee), which may let eligible buyers purchase with as little as a 5% deposit without paying LMI because the government guarantees part of the loan; the first home super saver scheme, which may let you save toward a deposit inside your super within set caps; and help to buy, a shared-equity scheme where the government takes a stake to shrink what you borrow. all three have eligibility rules and price caps that change, so check the current rules at firsthomebuyers.gov.au and ato.gov.au for the super saver.
the queensland layer is where this page earns its keep: the queensland first home owner grant for eligible buyers of a new or substantially renovated home, and transfer duty (stamp duty) concessions for eligible first home buyers, both administered by queensland revenue office. i've broken both of those out below with the gov source for each, because the numbers move and i'd rather point you at the official figure than write one that ages badly.
the important bit: some of these can work together. a queensland buyer might use a federal deposit scheme and a state duty concession on the same purchase. what i'd do is not try to optimise this solo, the team at finance lab can map which combination you may be eligible for against your actual situation, which is far more useful than a generic checklist.
| layer | what it may do | where to check |
|---|---|---|
| federal: 5% deposit scheme | may let eligible buyers purchase with a 5% deposit without paying lmi | firsthomebuyers.gov.au |
| federal: first home super saver | may let you save toward a deposit inside super within set caps | ato.gov.au |
| federal: help to buy | shared-equity, the government takes a stake to shrink what you borrow | firsthomebuyers.gov.au |
| qld: first home owner grant | one-off payment for eligible buyers of new or substantially renovated homes | qro.qld.gov.au |
| qld: transfer duty concession | may reduce or remove duty for eligible first home buyers | qro.qld.gov.au |
the qld first home owner grant, who qualifies
the queensland first home owner grant is a one-off payment for eligible first home buyers, and the catch most people miss is that it's generally aimed at new homes: buying or building a brand-new place, or in some cases a home that's been substantially renovated, rather than an established house. that single rule reshapes a lot of brisbane searches, because it nudges you toward the new house-and-land stock in the growth corridors if the grant is something you want to use.
broadly, who may qualify comes down to a few things: you're an individual (not a company or trust), you're an australian citizen or permanent resident, you and usually your partner haven't owned a home in australia before, the property is under a value cap, and you move in and live there as your home within a set timeframe. those are the shape of the rules, not the exact thresholds, because the value cap and the grant amount are exactly the kind of figures that change in a state budget.
so i'm deliberately not writing a dollar figure here. check the current amount, the value cap and the full eligibility criteria at qro.qld.gov.au, which is queensland revenue office, the body that actually administers it. that's the source of truth, and it's where the number will be right.
if you're not sure whether your plan (an established unit in the middle ring, say, versus new house-and-land out west) would even be eligible, that's a quick conversation worth having before you commit to a direction. book a chat with finance lab and they can tell you whether the grant is in play for the kind of property you're actually chasing.
the catch most people miss
the grant is generally aimed at new homes, building or buying brand-new, or in some cases substantially renovated, rather than an established house. that one rule nudges your search toward new house-and-land in the growth corridors if you want to use it.qld stamp duty concessions for first home buyers
stamp duty, which queensland calls transfer duty, is one of the biggest upfront costs of buying, and it's also where queensland first home buyers may get the most meaningful relief. the state offers transfer duty concessions for eligible first home buyers, and depending on the property value, an eligible buyer may pay reduced duty or, under a certain value, no transfer duty at all on a first home. that can be a serious chunk of cash that stays in your pocket or, more usefully, goes toward your deposit.
there's also a separate concession for first home buyers purchasing vacant land to build on, which matters in brisbane because so much of the affordable, grant-eligible stock is house-and-land in the growth corridors. so the duty rules and the grant rules tend to point you in the same direction.
as with everything money-shaped on this site, the value thresholds and the exact concession move, so i'm not pinning a figure. check the current transfer duty concession rules, the value cut-offs and the eligibility criteria at qro.qld.gov.au. there's a transfer duty estimator on there too, which is genuinely worth a few minutes because it turns an abstract worry into a real number for the place you're looking at.
here's what i'd actually do with this: work out your likely duty (after any concession you may be eligible for) before you set your price ceiling, not after. duty is part of the true cost of getting in, and knowing it early stops a nasty surprise at settlement.
the bit i'd flag
work out your likely duty, after any concession you may be eligible for, before you set a price ceiling, not after. there's a transfer duty estimator at qro.qld.gov.au that turns the worry into a real number.how much deposit do you need to buy in brisbane?
the deposit number is the one that nearly put me off the whole thing, so let me give you the honest version for brisbane. most lenders want somewhere between 5% and 20% of the price. twenty percent is the level where most lenders stop charging lenders mortgage insurance, so it's the cheapest structure if you can get there. below twenty percent you can usually still buy, you just either pay LMI or use a scheme that may waive it.
on a brisbane entry budget, the maths is friendlier than the inner-city numbers suggest, precisely because you're shopping the under-$600k bands in the corridors. a 5% deposit on an entry-priced home is a much smaller savings target than 20% on a citywide median, and if you qualify for the australian government 5% deposit scheme you may be able to buy at that 5% level without the LMI bill on top. that's the difference between "years away" and "this year" for a lot of people.
don't forget the costs that sit alongside the deposit: transfer duty (which a first home concession may reduce or remove), conveyancing, building and pest inspections, and a buffer for the first few months. these are real money and they're easy to under-budget. the queensland first home owner grant, if you're buying eligible new stock, can offset some of this, which is one more reason the grant-eligible corridors are worth a look.
what i'd do is work out your three numbers, deposit you've actually got, borrowing power, and any scheme you may qualify for, before you set a price ceiling. those three together decide your real budget far more than the suburb does. a broker, like the team at finance lab, can run your specific numbers, and that's worth doing before you fall in love with a listing.
rough guide only, also budget for transfer duty, conveyancing, inspections and a buffer; check current scheme rules and run your own numbers with a broker.
grab my $25k-deposit suburbs guide
the corridors and the kind of stock where a small deposit still opens the door in brisbane.
how to shortlist a brisbane suburb on a first home budget
once your numbers are sorted, shortlisting a suburb gets a lot less overwhelming. here's the order i'd go in.
first, pick your direction before your suburb. decide whether land or location matters more to you, then choose the corridor that fits: logan or moreton bay if you want a house and you'll trade commute for it, the middle ring if you'd rather a unit closer in. choosing a direction first cuts your search from a whole city down to a manageable strip.
second, pressure-test the commute and the basics for real. a cheap suburb an hour and a half from work in traffic isn't cheap once you count the time and the petrol. check the actual peak-hour trip, the train line, and whether the everyday stuff (a decent shop, a school if you'll need one) is there. live the week in your head, not just the open home.
third, match the suburb to your schemes. if you want the queensland first home owner grant, weight your search toward the new house-and-land areas where eligible stock actually exists. if you're using a deposit scheme with a price cap, make sure the suburb's typical prices sit under that cap, or you'll keep getting outbid out of your own budget.
fourth, look at a real spread of current listings in your shortlisted corridor before you commit, so your sense of "normal" price is based on this month's market, not last year's headline. and if you want a second set of eyes on whether a suburb fits your borrowing power and your scheme eligibility, the team at finance lab can sanity-check it. the goal isn't the cheapest postcode, it's the place where your budget, your life and the help you may be entitled to all line up.
queensland first home owner grant
a one-off payment for eligible first home buyers, generally for buying or building a new home (and in some cases a substantially renovated one), administered by queensland revenue office. who may qualify: individuals (not companies or trusts) who are australian citizens or permanent residents, who haven't previously owned a home in australia, buying under a value cap, and who move in and live there as their home within a set timeframe. the grant amount and the value cap change, so this is general information only, not a current figure. check the current amount, cap and full eligibility at qro.qld.gov.au. last reviewed june 2026.
last reviewed june 2026
queensland transfer (stamp) duty concession for first home buyers
queensland offers a transfer duty (stamp duty) concession for eligible first home buyers, which may reduce or, under a certain property value, remove the duty payable on a first home, with a separate concession available for eligible first home vacant land purchases. eligibility and the value thresholds change, and this is general information only, so don't treat any figure here as current. check the current concession rules, value cut-offs and eligibility, and use the transfer duty estimator, at qro.qld.gov.au (queensland revenue office). last reviewed june 2026.
last reviewed june 2026
 hear it on the showtop 3 first home in brisbane with a $23,000 deposit
 hear it on the showunderstanding how home grants work!
 hear it on the showhow to find properties below $500k
also by location: what it costs to buy a first home first home buyer Queensland
frequently asked questions
what are the cheapest suburbs in brisbane to buy a first home?
the cheapest entry options in brisbane tend to sit in the outer corridors rather than any single famous suburb, mainly the logan corridor to the south, the ipswich and springfield areas to the west, and the moreton bay and caboolture area to the north, where an entry budget still buys a house. closer in, the cheapest stock shifts to two-bedroom units and townhouses. i won't name a suburb-and-price as fact because brisbane moves fast, so check current listings in those corridors to see what's actually cheapest this month. this is general information only.
how much is the queensland first home owner grant?
the queensland first home owner grant is a one-off payment for eligible first home buyers, generally for new homes, but i'm deliberately not pinning a dollar figure here because the amount and the value cap change, sometimes in a state budget. check the current amount and the full eligibility at qro.qld.gov.au, which is queensland revenue office and the official source. this is general information only, not personal advice, so confirm the current rules before you rely on them.
do first home buyers pay stamp duty in queensland?
queensland calls it transfer duty, and eligible first home buyers may get a concession that reduces it or, under a certain property value, removes it entirely, with a separate concession for eligible vacant land purchases. whether you pay, and how much, depends on the property value and your eligibility, and the thresholds change. check the current concession rules and use the estimator at qro.qld.gov.au. this is general information only; confirm your own situation with the current rules or a broker.
how much deposit do i need to buy a first home in brisbane?
most lenders want between 5% and 20% of the price; 20% is where most stop charging LMI, but you can usually still buy below that by paying LMI or using a scheme that may waive it, like the australian government 5% deposit scheme if you qualify. on brisbane's under-$600k entry stock, a 5% deposit is a much smaller target than people expect, but remember to budget for duty, inspections and a buffer too. this is a rough guide only; check the current scheme rules at firsthomebuyers.gov.au and run your own numbers with a broker.
can you buy a first home in brisbane under $600k?
yes, genuinely, you just have to look in the right places. under $600k in brisbane realistically means houses in the outer corridors (logan, ipswich and springfield, moreton bay and caboolture) or units and townhouses closer in. it's a real band, not a fantasy, it's just not the inner-ring houses you see in the news. check current listings in those corridors to see what your budget opens up. this is general information only, and prices move, so treat it as a starting point.
what is a realistic first home budget in brisbane in 2026?
a realistic budget isn't a single number, it's your deposit plus your borrowing power plus any scheme you may qualify for, minus the duty and upfront costs of getting in. for a lot of brisbane first home buyers that lands them shopping the under-$600k corridors and the middle-ring unit market, but yours depends on your income, your savings and whether a duty concession or deposit scheme is in play. i'd work those numbers out before setting a price ceiling. this is general information only; a broker like the team at finance lab can run your actual figures.
general information only, not personal financial advice. Finance Lab, Credit Representative Number 425945, authorised under Australian Credit Licence Number 389328. scheme, grant and cost figures are explanatory only, change regularly, and were last reviewed june 2026. always confirm current rules with the relevant government source.