which perth suburbs are affordable for first home buyers right now?
i'll be honest with you up front: i'm not going to name a suburb and slap a price on it, because perth prices have been moving and anything i write today could be wrong by the time you read it. what i can do is point you at the right parts of the map, because perth has a pattern, and once you see it the affordable suburbs stop feeling like a secret.
the rule of thumb in perth is simple. the closer you get to the river and the coast in the inner ring, the more you pay. the affordable stuff lives in the outer growth corridors where the new estates and the older established pockets are. that means looking north past the joondalup line, south through the cockburn, kwinana and rockingham corridor, east toward armadale and the foothills, and the value pockets in between. these are real places where first home buyers actually land, not leftovers.
so the honest answer to "which suburbs" is: the ones in those outer corridors, filtered by your budget and your commute, checked against current listings on the day you're looking. don't trust a "cheapest suburbs in perth" listicle from last year. open realestate.com.au or domain, set your max price, draw your search area around one of those corridors, and see what's genuinely selling. that live snapshot beats any number i could give you.
the bit i'd flag
perth prices have been moving, so any suburb number you read can be stale fast. set your max price on realestate.com.au or domain and check what is genuinely selling on the day you look, not last year's cheapest-suburbs listicle.what counts as affordable in perth in 2026?
"affordable" is one of those words everyone uses and nobody defines, so let me give you a way to actually pin it down for yourself.
affordable isn't a magic price tag, it's the home you can buy and still keep your life. the proper way lenders think about it is serviceability: can you make the repayments on this loan, at the rates they stress-test you against, and still cover everything else? a home is affordable for you if the repayment, the rates and water, the insurance, and the body corp if there is one all fit inside your income with breathing room left over. that's the version that matters, because the bank uses it and so should you.
perth has a genuine edge here compared to sydney or melbourne. it's consistently one of the more reachable capital cities for a first home, which is exactly why the under-$500k search is realistic in perth when it's a fantasy elsewhere. that doesn't mean every suburb is cheap, it means the floor is lower, so a normal first home buyer income stretches further. for current perth median figures, check a recent source like the abs or corelogic rather than my word, but the takeaway holds: perth rewards buyers who are realistic about location.
my take: set your affordable number from the bottom up, not the top down. start with what you can borrow and what deposit you've got, land on a comfortable monthly repayment, and let that decide your max price. then go find the suburb. doing it the other way, falling for a house and reverse-engineering the budget, is how people overcommit.
my take
set your affordable number from the bottom up, not the top down. start with what you can borrow and the deposit you have, land on a repayment you can hold, and let that decide your max price, then go find the suburb.affordable suburbs in perth under $500k (by region)
perth is one of the few capitals where "under $500k" is a real search, not wishful thinking. here's how i'd break the map into regions so you know where to point your filter. again, i'm giving you corridors, not fixed prices, so check current listings in each before you commit to anything.
north corridor: the run up through wanneroo, and the established and newer pockets around the joondalup line. handy if you want the northern beaches and don't mind a longer trip to the city. plenty of house-and-land in the newer estates further out, plus older homes closer in that can sit in budget.
south and the kwinana corridor: cockburn, kwinana, and the rockingham and baldivis area. this is classic first home buyer country, lots of newer estates, good value, and the train line south helps the commute. baldivis in particular has been a magnet for new builds.
east and the foothills: the armadale corridor and the suburbs running east toward the hills. some of the most affordable established homes in perth sit through here, and it's worth a look if you want a house and land rather than an apartment or townhouse.
then there are the in-between value pockets and the apartment and townhouse options closer to transport, which can land under budget even when the freestanding house in the same suburb doesn't. the move is: pick one or two regions that suit your work and life, set your filter to under $500k, and see what's actually on the market this week. if the search comes up thin in one corridor, slide to the next one rather than blowing your budget to stay put.
| corridor | example suburbs | indicative range |
|---|---|---|
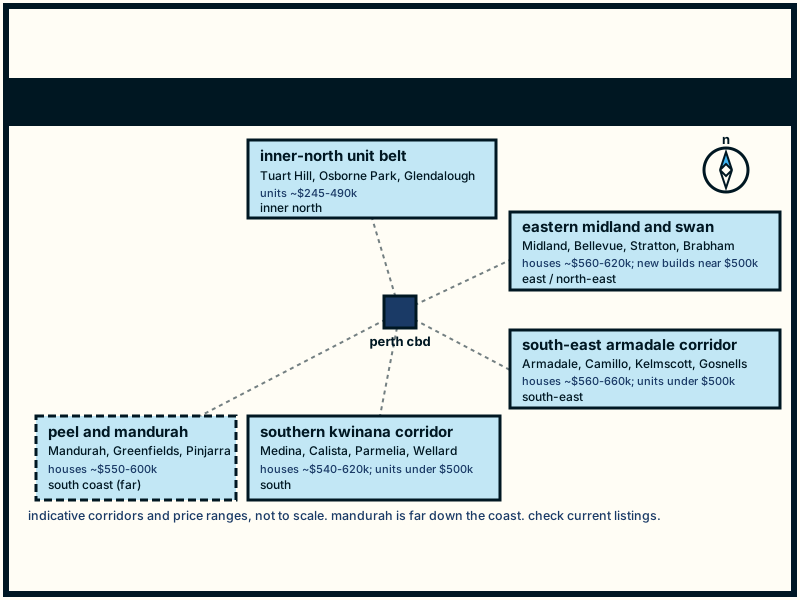
| the southern kwinana corridor | Medina, Calista, Parmelia, Orelia | older houses roughly $540k to $620k; some units, townhouses and smaller blocks dip under $500k, check current listings |
| the south-east armadale corridor | Armadale, Camillo, Kelmscott, Maddington | houses roughly $560k to $660k after strong recent growth; units and townhouses are more likely to come in under $500k, check current listings |
| the eastern midland and swan corridor | Midland, Bellevue, Middle Swan, Stratton | established houses roughly $560k to $620k; new house-and-land and townhouses can sit nearer the $500k mark, check current listings |
| the coastal south peel and mandurah | Mandurah, Greenfields, Pinjarra, Coodanup | houses roughly $550k to $600k; a meaningful number of houses and units still trade under $500k here, check current listings |
| the inner-north unit belt | Tuart Hill, Osborne Park, Glendalough, Balga | units roughly $245k to $490k; houses here are well above $500k, check current listings |
| region | where to look | what it suits |
|---|---|---|
| north corridor | wanneroo and the pockets around the joondalup line | northern beaches access, house-and-land further out, older homes closer in |
| south and kwinana | cockburn, kwinana, rockingham and baldivis | classic first home buyer country, newer estates, train line south |
| east and foothills | the armadale corridor toward the hills | some of the most affordable established homes, good for house and land |
| in-between pockets | apartments and townhouses near transport | can land under budget even when the freestanding house in the same suburb does not |
watch: how i'd actually run a sub-$500k search without losing the plot.
first home buyer schemes that apply in perth and wa
this is the part that genuinely changes the maths, so it's worth getting your head around. as a first home buyer in perth you've potentially got three different things working for you at once, and they're not the same as the schemes in other states.
first, the wa first home owner grant, a one-off state grant aimed at new homes. second, first home owner transfer duty relief, wa's version of stamp duty help, which can wipe out or reduce the duty you'd otherwise pay. third, keystart, the wa government's own lender that lets eligible buyers in with a much smaller deposit and no lenders mortgage insurance. on top of those, there are commonwealth schemes that apply nationally, like the first home guarantee, which i cover on my main first home buyer guide.
the important bit: these don't all apply to the same purchase in the same way. the grant is for new builds. the duty relief and keystart can apply to established homes too. so the right mix depends on whether you're buying brand new, off the plan, or an existing home. i've put dated, government-cited summaries of the two big wa ones below so you can see roughly how they work, but every one of them has fine print and the thresholds change, so check the current rules on the official wa government pages before you bank on anything.
honestly, this is exactly where a broker earns their keep. my dad, john kefalianos, is a mortgage broker, and the thing he sees over and over is buyers who qualified for more help than they realised, or who structured the purchase the wrong way and lost a concession. so before you sign anything, it's worth having someone map your specific situation against all three.
| scheme | what it does | what it applies to |
|---|---|---|
| wa first home owner grant | one-off state grant toward your purchase | new builds, off-the-plan, house-and-land, substantial renovations, not standard established homes |
| transfer duty relief | wa's stamp duty help, can wipe out or reduce duty up to set thresholds | established and new homes, separate thresholds for vacant land |
| keystart | wa government lender, smaller deposit and no lmi for eligible buyers | established homes too, with income and price caps, designed as a stepping stone |
worth knowing
these do not all apply to the same purchase the same way, so the right mix depends on whether you buy new, off the plan or established. this is where a broker earns their keep, mapping your situation against all three before you sign.the wa first home owner grant, who may qualify
the wa first home owner grant, usually shortened to fhog, is a one-off payment from the western australian government to help first home buyers into a new home. i'm deliberately not quoting the dollar figure here because amounts and caps get reviewed, so check the current amount on the official revenuewa page rather than trusting a number off a blog.
here's the honest version of who it's really for. the grant is aimed at new homes, so newly built houses, off-the-plan apartments, house-and-land packages, and substantially renovated dwellings count, but a standard established second-hand home does not. that's the single most common surprise, people assume any first home gets the grant, and it doesn't, it's a new-build incentive.
beyond that, the usual shape of the rules is: at least one applicant needs to be an australian citizen or permanent resident, you and any co-applicant generally can't have owned residential property in australia before, you need to be buying as an individual rather than through a company or trust, and you have to actually live in the home as your main residence for a set continuous period that starts within a window after settlement or completion. there's also a property value cap, which has been lifted in recent updates, so the threshold you read last year may be out of date.
who may qualify, then: a genuine first-timer buying or building something new, who'll live in it. if that's you, the grant is real money toward your purchase. just confirm every condition against the current rules on the wa government site, because eligibility is decided on the detail, not the vibe.
keystart, the wa low-deposit alternative path
keystart is the part of the wa setup that surprises people the most, so i want to give it proper space. it's a home lender owned by the western australian government, and its whole reason for existing is to get eligible western australians into a home with a smaller deposit than a normal bank would accept, and without paying lenders mortgage insurance.
that second part is the big one. normally, if your deposit is under twenty per cent, a lender makes you pay lmi, which can run into many thousands of dollars and adds nothing to your equity. keystart's model is built to skip that for eligible borrowers, which can be the difference between buying this year and saving for another two. the trade-off is that keystart loans come with their own rules: there are income limits, which were lifted in 2026, and property price caps for the perth metro area, plus the expectation that you refinance to a mainstream lender down the track once your equity and income allow.
i'm not going to lock in the exact deposit percentage, income ceiling, or price cap here, because keystart adjusts these to match the market and they've moved recently. check the current figures on keystart's official site. what i'll say plainly is the shape of it: low deposit, no lmi, income and price limits, designed as a stepping stone rather than a forever loan.
here's how i'd think about it. keystart can be the lowest-deposit way into perth for buyers who'd otherwise be locked out, but it's not automatically the cheapest loan over the long run once you factor in the rate and the plan to refinance. that's a real decision, not a no-brainer, and it's worth running both paths, keystart versus a standard low-deposit loan with the schemes, before you pick. a broker can model that side by side for you.
one to watch
keystart can be the lowest-deposit way into perth for buyers who would otherwise be locked out, but it is not automatically the cheapest loan long term once you factor in the rate and the plan to refinance. run both paths, keystart versus a standard low-deposit loan with the schemes, before you pick.how much deposit do you need to buy in perth?
this is the question that keeps most first home buyers up at night, so let's be straight about it.
the textbook answer is twenty per cent of the purchase price, because that's the level where you avoid lenders mortgage insurance with a normal lender. on a perth home that's a serious chunk of cash, and saving it can take years. but twenty per cent is the comfortable version, not the minimum.
in reality, perth first home buyers get in with a lot less. many mainstream lenders will take a five per cent deposit if your income supports the loan, you just pay lmi on top. the first home guarantee, a commonwealth scheme, lets eligible buyers in with as little as five per cent and skips the lmi entirely, because the government guarantees the gap. and keystart, as i covered above, is built for an even smaller deposit with no lmi for eligible wa buyers. so the practical floor in perth is much lower than twenty per cent.
what i'd actually do: don't anchor on a single percentage, work out your true cash-needed number. that's your deposit plus the buying costs people forget, transfer duty if any applies after the first home concession, conveyancing and legal fees, building and pest inspections, loan setup costs, and a buffer for moving and the first few months. add those up, then look at which low-deposit path you qualify for, because that decides how big the deposit slice really needs to be. i'd nail down your borrowing capacity and your eligible schemes first, then the deposit target stops being a scary guess and becomes an actual figure.
rough guide only, deposit paths and thresholds change, check the current rules for each before you bank on them.
grab my deposit roadmap
work out your true cash-needed number, deposit plus the buying costs people forget, before you set a suburb target.
how to shortlist a perth suburb on a first home budget
once you know your number, the suburb hunt is the fun part, but it's easy to do badly. here's the method i'd use, in order, so you don't fall in love with the wrong street.
start with your real budget, the one from the deposit and serviceability work, not your dream number. then pick your non-negotiables: how long a commute can you actually live with, do you need to be near a train line, do you want a freestanding house or are you open to a townhouse or apartment to get a better location for the money. write those down before you look at a single listing, because they stop you talking yourself into something that doesn't fit.
next, choose a corridor, not the whole city. perth is big, and trying to compare a northern beaches suburb with an eastern foothills one with a southern estate at the same time just scrambles your head. pick the one or two regions that suit your work and life from the breakdown above, and go deep there. set your price filter, draw your search area, and look at what's genuinely selling this week, not what sold last year.
then do the unglamorous homework. drive the suburb at different times, check the commute in real traffic, look at what's planned nearby, and sanity-check that the schemes you're counting on actually apply to the kind of property you're looking at, new versus established changes everything. if a corridor keeps coming up short of your budget, move to the next one rather than stretching, there's almost always another affordable pocket in perth if you stay flexible on location. when you've got a shortlist and a number you trust, that's the moment to bring in finance and lock in your pre-approval, so you can move fast when the right one shows up. if you want a hand mapping the wa schemes to your situation, you can book a chat with the team at finance lab.
wa first home owner grant (fhog)
as at june 2026: the wa first home owner grant is a one-off state government payment to help eligible first home buyers buy or build a new home in western australia. it applies to new builds, off-the-plan purchases, house-and-land packages and substantially renovated homes, not standard established homes. eligibility turns on residency, never having owned residential property before, buying as an individual, and living in the home as your main residence for a set continuous period. a property value cap applies and has been increased in recent updates. the grant amount, the value cap and the full conditions are reviewed periodically, so check the current rules and amount before you rely on them. official source: revenuewa, first home owner grant, www.wa.gov.au/organisation/department-of-treasury-and-finance/first-home-owner-grant-fhog. general information only, not financial advice.
last reviewed june 2026
wa first home owner transfer duty relief (stamp duty)
as at june 2026: in western australia, stamp duty is called transfer duty, and eligible first home buyers can pay no duty or a reduced concessional rate up to set property value thresholds, for both established and new homes, with separate thresholds for vacant land. the wa government increased these thresholds in 2026, lifting the full-exemption and concession caps, so older figures may be out of date. the exact thresholds, the concession scale and the eligibility conditions change, so check the current rules before budgeting for any duty saving. official source: revenuewa, first home owner rate of duty fact sheet, www.wa.gov.au/government/publications/duties-fact-sheet-first-home-owner-rate. general information only, not financial advice.
last reviewed june 2026
 hear it on the showunderstanding how home grants work!
 hear it on the showhow to find properties below $500k
 hear it on the showhow to start saving for a deposit!
also by location: what it costs to buy a first home first home buyer Western Australia
frequently asked questions
what are the cheapest suburbs in perth to buy a first home?
the most affordable suburbs in perth sit in the outer growth corridors rather than the inner ring, so look north past joondalup, south through the cockburn, kwinana, rockingham and baldivis corridor, and east toward armadale and the foothills. i won't name a single "cheapest" suburb with a price, because perth prices move and the answer changes, so set your max budget on realestate.com.au or domain, search one of those corridors, and see what's genuinely selling this week. this is general information only, always check current listings.
how much is the wa first home owner grant?
the wa first home owner grant is a one-off state government payment for eligible first home buyers buying or building a new home, but i'm not going to quote the dollar figure here because the amount and the property value cap get reviewed and i don't want you banking on an out-of-date number. check the current amount on the official revenuewa page (www.wa.gov.au/organisation/department-of-treasury-and-finance/first-home-owner-grant-fhog). it applies to new builds, not standard established homes. general information only, check the current rules for your situation.
what is a keystart loan and who is it for?
keystart is a home lender owned by the western australian government, built to get eligible wa buyers into a home with a much smaller deposit than a normal bank requires and with no lenders mortgage insurance. it's aimed at people who can comfortably make repayments but haven't been able to save a full deposit, and it comes with income limits and property price caps, with the expectation you refinance to a mainstream lender later. the exact limits changed in 2026, so check the current figures on keystart's official site. it's a stepping-stone loan, not automatically the cheapest long-term, so it's worth comparing. general information only.
how much deposit do i need to buy a first home in perth?
twenty per cent of the price is the comfortable level where you avoid lenders mortgage insurance, but the real floor in perth is much lower. many lenders accept a five per cent deposit with lmi, the commonwealth first home guarantee lets eligible buyers in with as little as five per cent and no lmi, and keystart is built for an even smaller deposit with no lmi for eligible wa buyers. don't anchor on one percentage, work out your full cash-needed number including buying costs, then match it to whichever low-deposit path you qualify for. this is general information only, not financial advice.
can you buy a first home in perth under $500k?
yes, and that's genuinely one of perth's strengths, it's consistently one of the more reachable capital cities, so an under-$500k first home is a realistic search here when it isn't in sydney or melbourne. you'll find the most options in the outer corridors, north, south through the kwinana belt, and east toward armadale, and townhouses or apartments can land under budget closer to transport. check current listings on the day you're looking rather than trusting an old number. general information only, always confirm with live market data.
what is a realistic first home budget in perth in 2026?
a realistic budget isn't a single figure, it's the number that comes out of your deposit, your borrowing capacity and a repayment you can comfortably hold alongside the rest of your life, so it's personal to you. perth's lower price floor compared to the eastern capitals means a normal first home buyer income stretches further here, but the right move is to set your budget from the bottom up, what you can borrow and save, not from a house you've fallen for. check current perth medians via a recent source like corelogic or the abs, and get your borrowing capacity confirmed before you shop. general information only, not financial advice.
general information only, not personal financial advice. Finance Lab, Credit Representative Number 425945, authorised under Australian Credit Licence Number 389328. scheme, grant and cost figures are explanatory only, change regularly, and were last reviewed june 2026. always confirm current rules with the relevant government source.